
-
- monday: 8:00AM – 7:00PM
- tuesday: 8:00AM – 7:00PM
- wednesday: 8:00AM – 7:00PM
- thursday: 8:00AM – 7:00PM
- friday: 8:00AM – 7:00PM
-
Your Local CrossCountry Mortgage Loan Officer
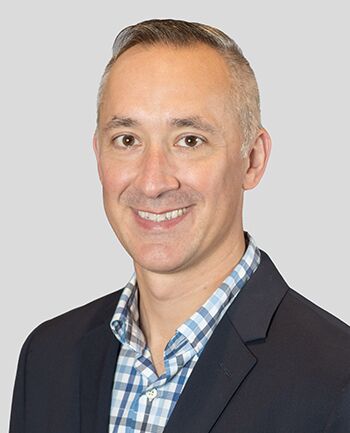
Tom Lade


Ohio’s #1 Retail Mortgage Lender
I’m Tom Lade, a loan officer serving Powell, Columbus and communities across Central Ohio. Buying a home, moving into your next one or using your home equity should not feel complicated. I’ll explain your options clearly, solve problems early and help you move forward with confidence.
Since 2012, I’ve guided more than 1,200 homebuyers and homeowners through the mortgage process. From first-time homebuyers and move-up buyers to self-employed borrowers, real estate investors and current homeowners, I’ve used many loans to help many different situations.
At America’s #1 Retail Mortgage lender, I offer Non-QM loans designed for self-employed borrowers and real estate investors, including bank statement, asset qualifier, 1099, P&L and DSCR options. I can also help you explore a HELOC for renovations, debt consolidation, investment opportunities or accessing equity without refinancing. Plus, my Buy Now, Sell Later program may let you purchase your next home before selling your current one.


Tom’s Reviews
My Videos
Guides and resources


My social posts
Compare two mortgage loans to see which one will save you money.
Enter the basic terms for two different loans to calculate the difference between them and see a cost comparison.
This calculator is being provided for educational purposes only. The results are estimates based on information you provided and may not reflect CrossCountry Mortgage, LLC product terms. The information cannot be used by CrossCountry Mortgage, LLC to determine a customer’s eligibility for a specific product or service.


Inspiration for your home loan journey


Frequently asked questions
-
Refinancing costs typically range from 2% to 6% of the loan amount and include fees such as appraisal, title insurance, and closing costs. Factors like your loan type, location, and credit score can significantly impact these expenses. Our team can help to provide strategies that can help minimize costs.
-
To determine how much home you can afford, you’ll want to assess your financial situation. This includes your income, expenses, and debt-to-income ratio, to ensure your mortgage fits comfortably within your budget. A general guideline is to spend no more than 28% of your gross monthly income on housing costs and 36% on total debt.
-
A good credit score typically starts at 620 for conventional loans, while FHA and VA loans may accept scores as low as 500, though higher scores offer better terms. A strong credit score can help you secure lower interest rates, saving you significant money over the life of a home loan.
-
A Home Equity Line of Credit (HELOC) is a revolving line of credit that allows homeowners to borrow against the equity in their home. HELOCs function like a credit card, giving access to funds up to a set limit, which can be used for expenses like renovations or debt consolidation. You only pay interest on the amount you borrow, and the repayment terms typically include a draw period followed by a repayment period.
-
To calculate your mortgage payments, start with your loan amount, interest rate, and loan term. Your payment will depend on the interest charged over time and the repayment schedule. You can use a monthly mortgage payment calculator or connect with us to learn more.
-
Non-QM loans use expanded home financing criteria to give borrowers income and credit flexibility. From qualifying with bank statements or 1099 income to purchasing investment properties, Non-QM loans open doors to homeownership many don’t realize are available.
-
Also known as Investor Cash Flow loans, DSCR loans are designed to help real estate investors secure financing with their rental property’s cash flow. Instead of relying on personal income, DSCR loans use the debt service coverage ratio (DSCR) to qualify.
DSCR is calculated by dividing the monthly rental income by principle, interest, property taxes, homeowners insurance and association dues.
-
Since Non-QM loans don’t follow traditional guidelines, they’re considered riskier. That’s why lenders often require a higher down payment, interest rate and other terms.
But Non-QM loans are a safe financing option that benefits many homebuyers. Talk to a CCM loan officer to learn what’s right for you.
-
Bank Statement loans allow you to qualify for a mortgage using your bank statements instead of tax returns. These loans are designed for borrowers who have strong credit and finances but don’t have traditional income, like self-employed workers.
To qualify, you’ll use the average of your deposits over a 12- or 24-month period. If your work doesn’t provide a W-2, this may be the loan for you.
-
ITIN loans give you a way to qualify for home financing without a Social Security number. Instead, your Individual Tax Identification Number (ITIN) makes homeownership possible.
At CrossCountry Mortgage, we provide numerous ways to qualify using an ITIN. Bank statements, liquid assets, 1099 income and more can all be used to buy a home with our ITIN loan.
-
No. Conventional loans follow criteria established by the Consumer Financial Protection Bureau (CFPB). Non-QM loans use different standards that provide flexibility for borrowers who may not meet conventional requirements due to the type of home being purchased, financial circumstances or non-traditional income or employment.