What is sweat equity in homeownership?
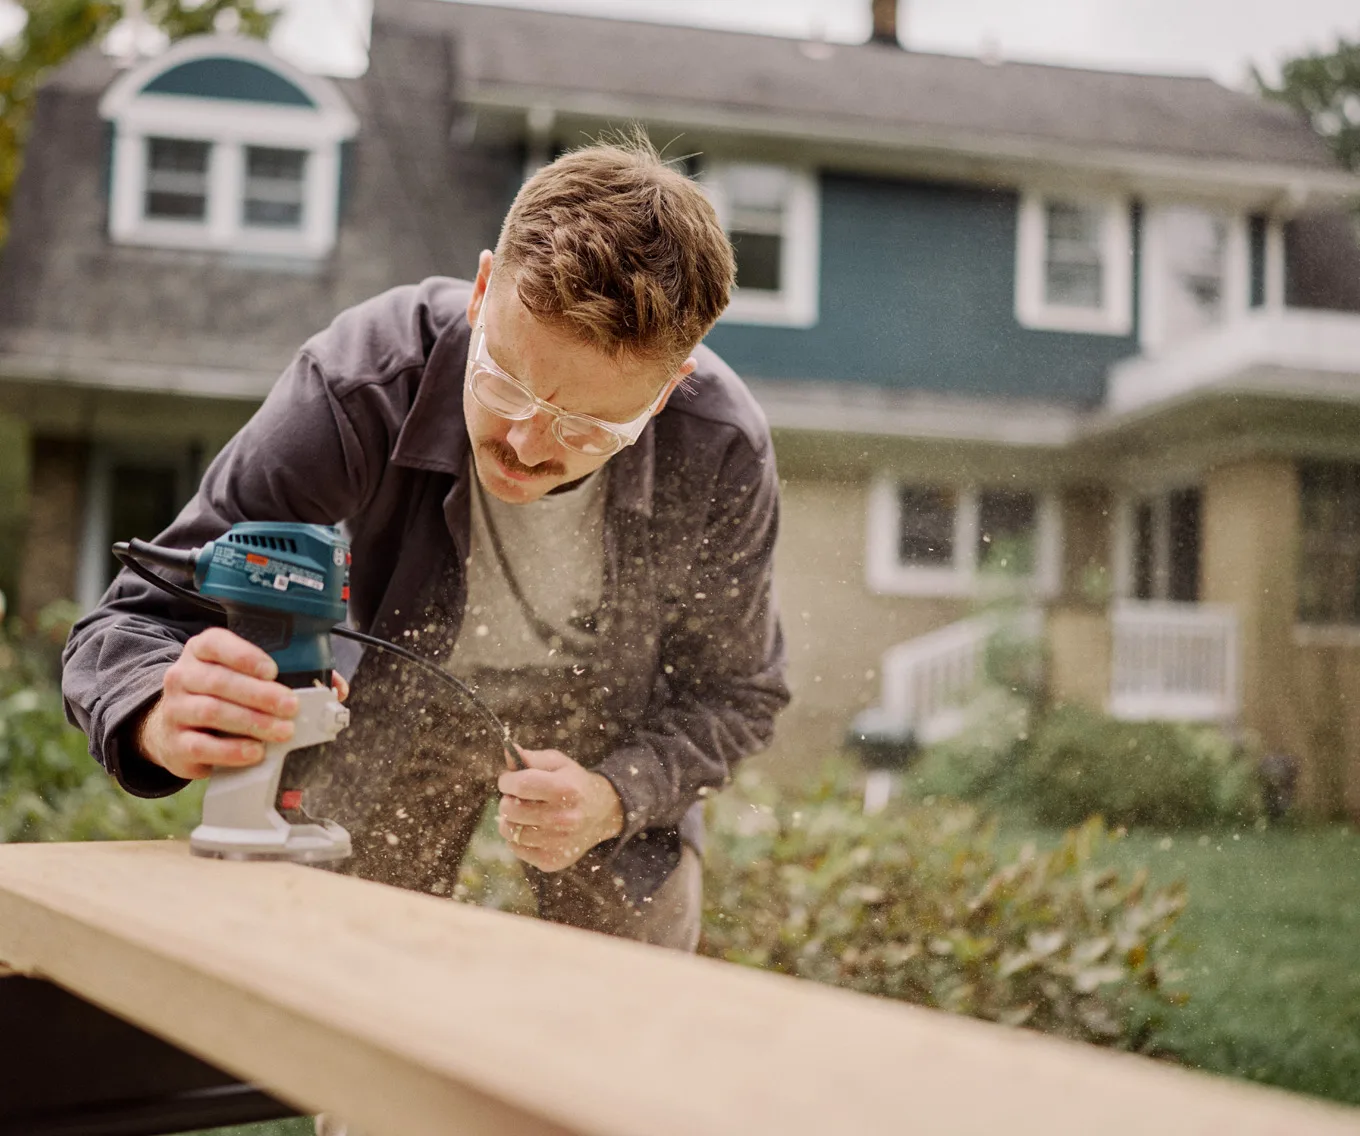
Sweat equity is the value or ownership interest someone may create through labor, skills and time instead of a direct cash investment. In homeownership, it can mean improving a property by doing your own repairs and upgrades, such as painting, flooring, or basic renovations. Doing the work yourself may reduce contractor costs while potentially contributing to the value of the home.
The contrast with traditional cash equity is fairly straightforward: cash equity comes from money invested in a property or changes in the property’s value, while sweat equity refers to value potentially created through your own work.
Sweat equity arrangements can also involve agreements that outline how physical labor and home improvements count toward an ownership or financial interest in a property. When multiple parties are involved, clearly documenting the arrangement can help everyone understand how contributions will be treated.
How sweat equity works in homeownership and real estate
Homeowners may create sweat equity by completing improvements themselves rather than paying someone else for the labor. Real estate investors may use a similar approach when renovating properties.
However, an appraiser doesn’t generally assign value based simply on the number of hours a homeowner spent working on a property. Instead, an appraisal considers the property’s completed condition, comparable properties, local market conditions and other relevant factors.
For example, suppose you buy a house for $250,000, spend $10,000 on materials, and handle the labor yourself. If the home later appraises for $280,000, the completed improvements may have contributed to the increase in value. However, other factors — including changes in the local housing market — may also affect the property’s value.
Keeping documentation such as before-and-after photos, receipts for materials, permits and contractor invoices can help create a record of the improvements made to the property.
Some affordable homeownership and nonprofit programs also incorporate sweat equity. Depending on the program, participants may be required to contribute labor, participate in construction or complete homeownership education as part of the process.
Using sweat equity toward a down payment
Some mortgage, affordable housing or assistance programs may allow eligible sweat equity to count toward a borrower’s required contribution, down payment or closing costs.
Whether sweat equity is permitted — and how much may be recognized — depends on the specific loan or assistance program, lender requirements, property, type of work performed and other applicable guidelines.
When a program permits sweat equity, there may be requirements related to the type of work performed, documentation, completion of the improvements, inspections, appraisals or other program guidelines. The value recognized for mortgage purposes may also differ from the amount a homeowner believes their labor or improvements are worth.
If you’re considering using sweat equity as part of a home purchase, talk with a CrossCountry Mortgage loan officer before beginning work. They can help you explore available financing options and determine whether a particular program allows eligible sweat equity and what requirements may apply.
Habitat for Humanity’s sweat equity model
Habitat for Humanity is a nonprofit that partners with families to build or renovate affordable homes. Participating future homeowners may be required to complete sweat equity activities, which can include working on Habitat homes, participating in homeownership education or completing other approved activities.
These requirements are part of Habitat’s homeownership model and are separate from mortgage programs offered by CrossCountry Mortgage. Habitat’s approach provides one example of how structured labor and participation can be incorporated into an affordable homeownership program.
Specific Habitat requirements can vary by location and program, so prospective participants should check with their local Habitat for Humanity organization for current eligibility and sweat equity requirements.
How to calculate the value of sweat equity in a home
There isn’t necessarily one universal formula for calculating sweat equity. One way homeowners may think about it is by comparing the money invested in improvements with changes in the property’s market value.
For an illustrative example, suppose you buy a property for $300,000, invest $12,000 in materials and complete the labor yourself. If the home later appraises for $340,000, the improvements may have contributed to the increase in value.
However, it would not necessarily mean that the difference between the purchase price, material costs and later appraised value is the amount of sweat equity recognized by an appraiser, lender or mortgage program. Property values can change for many reasons, including market conditions, location, comparable sales and the quality and type of improvements completed.
Any increase in equity may become relevant when selling a home or exploring refinance or home equity financing options. Actual results depend on the property’s value, the quality of the work, local market conditions and other factors.
When sweat equity is part of an agreement involving multiple owners or investors, clearly defining how labor contributions will be valued can help avoid confusion later.
Tax considerations for sweat equity in homeownership
Home improvements can have tax implications, but the treatment of a homeowner’s own labor, materials, paid contractors and changes in property value can vary based on the circumstances and applicable tax rules.
Certain qualifying improvement costs may affect a home’s adjusted tax basis, while improvements may also affect local property tax assessments if they increase the property’s assessed value.
Tax laws and individual circumstances vary and can change over time. Keep records of improvement expenses, receipts and permits, and consult a qualified tax professional for guidance about your specific situation.
Pros and cons of leveraging sweat equity in homeownership
Benefits of sweat equity
- Completing certain home projects yourself may reduce the amount you spend on professional labor.
- DIY improvements give homeowners an opportunity to customize their space while potentially increasing its market value.
- Participating directly in the improvement of a home can create a sense of accomplishment and ownership.
- Some eligible mortgage, affordable housing or assistance programs may recognize certain forms of sweat equity, subject to applicable program requirements.
Risks and limitations of sweat equity
- Complex projects, including certain structural, electrical, plumbing or other specialized work, may require licensed professionals or permits.
- Poor workmanship could negatively affect a property’s condition or value.
- Spending more on improvements doesn’t guarantee an equivalent increase in the property’s market value.
- Improvements that are significantly different from comparable homes in the area may not produce the anticipated return.
- Mortgage and assistance programs that recognize sweat equity may have specific eligibility, documentation, appraisal, inspection or other requirements.
Consider your available time, skills, budget, local requirements and financial goals before taking on significant home improvement projects yourself.
How CrossCountry Mortgage can help with your home journey
CrossCountry Mortgage can help you explore financing options based on your homeownership goals and financial situation.
If you’re considering a property where you plan to contribute your own labor or complete improvements, a licensed loan officer can help you determine which available loan programs may fit your situation and whether eligible sweat equity can be considered under applicable program guidelines.
If you already own a home and have built equity through improvements or other increases in your home’s value, you can also explore home equity financing options that may be available to you.
Talk with a licensed CrossCountry Mortgage loan officer, get pre-approved when you’re ready, or use our online calculators to estimate payments and affordability.
FAQ about sweat equity in homeownership
-
It depends on the mortgage or assistance program. Some programs may allow eligible sweat equity to satisfy a portion — or potentially more — of a borrower’s required contribution, while other programs may not recognize sweat equity at all.
Requirements can vary based on the loan program, lender, property, work performed and other factors. Talk with a loan officer before relying on sweat equity as part of your home purchase.
-
Eligible work varies by program. Certain programs may recognize qualifying repairs or improvements performed by the borrower, while specialized work may need to be completed by licensed professionals.
Building codes, permits, inspections, appraisal requirements and program guidelines may also apply. Confirm eligibility and requirements with your lender before beginning work if you plan to use sweat equity as part of a mortgage transaction.
-
Home improvements may affect a property’s market value once the work is completed, but there is no guarantee that an increase in value will equal the cost of the project or the estimated value of the labor performed.
An appraiser considers the property’s overall condition, comparable properties, local market conditions and other relevant factors when developing an opinion of value.
-
Certain mortgage or assistance programs may recognize eligible sweat equity as part of a borrower’s required contribution. However, mortgage qualification depends on numerous factors, which may include income, credit history, debts, assets, property eligibility and applicable loan-program requirements.
If you have limited savings, a CrossCountry Mortgage loan officer can help you explore available mortgage and down payment assistance options and determine which programs may fit your circumstances.
-
Not necessarily. Property taxes are generally based on the property’s assessed value and applicable local tax rules rather than the amount of labor a homeowner personally contributes.
Certain improvements could potentially increase a property’s assessed value and therefore affect property taxes. Check with your local tax assessor or a qualified tax professional for information about your specific property and jurisdiction.